The Portmarnock Group Limited
Security company
£50,000Approximate insurance cost saving
Oak helped The Portmarnock Group Limited save approximately £50,000 on insurance and move from an arrangement lasting three years to a policy lasting 12 months.
Oak helps security companies, fire safety professionals, contractors, property owners and fleets present complex risks clearly and compare suitable cover.
Personal serviceSpeak to the broker handling your account.
Specialist experienceFocused on complex commercial risks.
Regulated networkGauntlet Risk Management Ltd, FRN 308081.
Claims supportHelp presenting covered claims to insurers.
Practical guidance on commercial insurance, written for business owners.
A practical guide to factory, machinery, stock, product liability, business interruption and supply chain insurance for UK manufacturers and firms.
Understand commercial property rebuild values, professional valuations, average clauses and business interruption before your next renewal for owners.
Prepare vehicle, driver, use, claims and risk control information early to make a clearer UK motor fleet insurance renewal submission for operators.
Browse Oak's full catalogue of specialist and commercial insurance routes. The priority sectors appear first; every category remains separately accessible.
Specialist insurance advice for guarding, door supervision, events, keyholding and security businesses across the UK.
Explore coverInsurance advice for fire risk assessors, fire engineers, consultants and businesses producing life safety reports.
Explore coverCover for firms installing, maintaining and commissioning alarms, CCTV, access control and life-safety systems.
Explore coverInsurance for commercial buildings, portfolios, blocks, mixed-use property and unusual construction across the UK.
Explore coverListed building insurance for UK owners of homes and commercial heritage property. Review reinstatement, occupancy and repair needs with Oak.
Explore coverFleet insurance advice for cars, vans and mixed commercial vehicle fleets across the UK.
Explore coverOak Sunbed Insurance can offer UV treatment liability up to £1 million, subject to underwriting and policy terms. Discuss equipment, premises and staff cover.
Explore coverInsurance advice for UK manufacturers, engineering firms, fabricators, processors and product businesses, built around their sites, machinery, people, products and supply chains.
Explore coverBroker-led insurance advice for established waste and recycling businesses, from collection and sorting to processing, storage and carriage.
Explore coverInsurance advice for commercial property investors with multiple sites, warehouses and mixed tenancies, covering reinstatement, rent loss and schedules.
Explore coverHard-to-place business insurance guidance after a decline, non-renewal or cancellation. Prepare clear records and a fair presentation for a fresh review.
Explore coverProfessional indemnity advice for consultants, contractors and specialist service businesses.
Explore coverLiability, contract works, tools and professional cover for specialist trades and contracting businesses.
Explore coverA considered combination of property, liability, interruption, cyber and management covers for UK businesses.
Explore coverCommercial insurance advice for UK microbreweries, distilleries and brew pubs, including production, stock, premises and visitor exposures.
Explore coverA coordinated insurance programme for eligible businesses combining property, liability, interruption and other commercial covers.
Explore coverLandlord insurance advice for UK commercial and residential property owners. Review buildings, tenants, liability, rent and vacancy conditions with Oak.
Explore coverOffice insurance for UK businesses and shops. Review premises, contents, stock, customers, staff and interruption cover with an Oak broker.
Explore coverInsurance for UK tradespeople and small contractors, with liability, tools, materials and contract work considered around declared activities.
Explore coverInsurance advice for eligible motor traders, including sales, servicing, repair, vehicle custody and road-risk exposures.
Explore coverBuildings insurance advice for blocks of flats, freeholders, managing agents and residential property companies.
Explore coverCommercial insurance advice for nursing homes and care homes, considering property, liability, staffing and continuity risks.
Explore coverCommercial boat insurance for UK operators, with marine cover considered against vessel use, operating waters, crew and equipment.
Explore coverInsurance advice for vacant commercial and residential buildings, including risk controls and insurer conditions during unoccupancy.
Explore coverInsurance considerations for UK holiday homes, second homes and short-term lets, including occupancy and guest use.
Explore coverConsider public liability insurance for UK businesses, contractors and firms that work with the public, with cover matched to your actual activities.
Explore coverDiscuss employers' liability insurance for UK businesses, including employee roles, payroll, temporary workers and subcontractor arrangements.
Explore coverReview cyber insurance for UK businesses, including incident response, data liability, system restoration and interruption, subject to policy terms.
Explore coverInsurance considerations for UK hospitality and leisure businesses, including premises, guests, staff, stock, equipment and interruption risks.
Explore coverWaste transfer station insurance guidance for MRFs and recycling facilities. Review fire separation, stock levels, battery risks and permit limits.
Explore coverScrap metal dealer insurance guidance on stock values, hot work, gas cylinders, batteries, vehicles in custody and liability.
Explore coverSkip hire insurance for UK operators and skip lorries. Review motor, liability, skips and depot risks with Oak, subject to insurer acceptance and policy terms.
Explore coverRecycling insurance after claims, hazardous stock events or non-renewal. Prepare a clear chronology, evidence of improvements and renewal records.
Explore coverPrecision engineering insurance for UK metal fabricators and CNC firms. Review critical machines, customer property, tolerances, design and liability.
Explore coverHGV fleet insurance for established UK hauliers. Review motor, goods in transit, haulier's liability, depots and interruption with Oak.
Explore coverWarehouse insurance for UK distribution businesses. Review own and customers' goods, warehousekeepers' liability, handling equipment and interruption.
Explore coverInsurance advice for UK plant hire companies with excavators, cranes and telehandlers: owned and hired-in plant, wet and dry hire, off-hire, theft and liability.
Explore coverA careful guide to insurance questions for UK renewable energy installers: liability, design, workmanship, contract works and the limits of each policy.
Explore coverInsurance considerations for UK solar PV installers: roof work, electrical risk, workmanship exclusions, generation guarantees and contract works.
Explore coverWhat UK EV charger installers should discuss with a broker: electrical liability, groundworks, third-party sites, commissioning and contract terms.
Explore coverTwo distinct pathways: liability for domestic and SME battery installers, and the separate construction and operational route for commercial BESS owners and operators.
Explore coverInsurance questions specific to heat pump installers: refrigerants, hot work, commissioning, water damage and design sizing.
Explore coverCladding remediation insurance review for UK contractors. Discuss exclusions, building height, materials, surveys, design and historic exposure, subject to underwriting.
Explore cover
Manned guarding, door supervision, keyholding, mobile patrol, CCTV and close protection each carry distinct liability and contractual exposures. We explain your activities clearly when approaching insurers.
Fire risk assessors, consultants, installation contractors and commercial property owners each carry distinct professional and property exposures. We gather the information insurers need before approaching them.
Google rating checked 19 October 2026. The rating and review count may change.
“Oak Insurance Brokers were able to help me get a great deal on property insurance when I was struggling to get quotes from elsewhere.”
“Josh took the time to understand my needs in detail and offered tailored advice that felt genuinely personalised.”
“Josh at Oak Insurance Brokers helped our business with Fleet Insurance for work vehicles along with full liability cover for our high-risk line of work.”
Finding the right insurance market starts with understanding the risk.
Oak gathers the detail insurers need first, then approaches the insurance markets that appear appropriate for the business. Cover is never guaranteed: insurer acceptance, terms and conditions apply.
Oak Brokers Limited, trading as Oak Insurance Brokers, is an appointed representative of Gauntlet Risk Management Ltd (FCA firm reference number 308081). Gauntlet Risk Management Ltd is the regulated principal firm, not an insurer.
Discuss your renewalOak helps UK sunbed and tanning salons consider suitable business insurance for premises, equipment, liability, products, employees and business interruption, subject to insurer acceptance and policy terms.
Discuss your salon
Oak looks beyond the headline premium to the activities, wordings, limits, conditions and claims scenarios that determine whether a policy is suitable.
We identify the underwriting detail needed before insurers are approached.
Significant terms, exclusions, limits and conditions are considered alongside cost.
You can speak directly to the person handling your insurance, including when a claim arises.
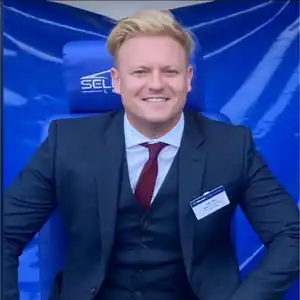
16 years working in insurance.
Joshua Bell, Oak's founder, has worked in insurance for 16 years. Oak was founded to give businesses direct access to experienced commercial insurance advice. The aim is simple: understand the business properly, present the risk accurately and explain the meaningful differences between the options.
Read the full storyNo anonymous call centre and no generic comparison journey.
We establish the business, activities, exposures and renewal priorities.
Clear information gives underwriters a better basis on which to respond.
We explain significant differences so you can make an informed decision.
Tell us what you do, what needs protecting and when the policy renews. We'll take it from there.